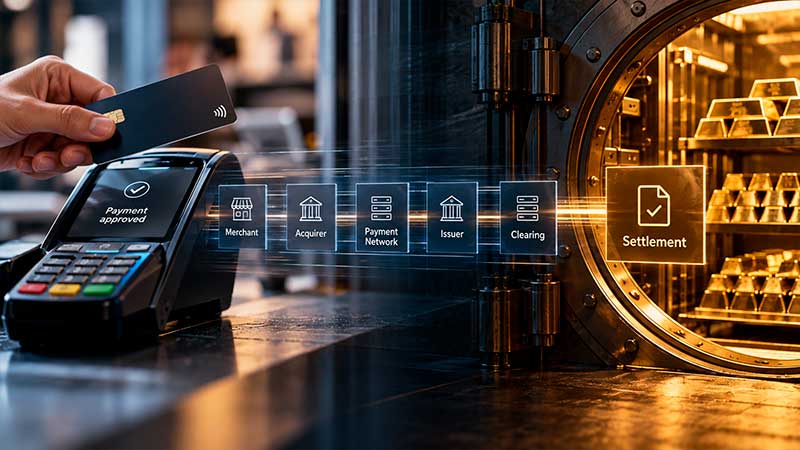
Payment Is Not Settlement
Modern systems are extraordinarily good at moving instructions. A card is tapped. A transfer is initiated. A balance changes. Confirmation appears almost immediately.
The experience feels complete.
The underlying financial obligation may not be.
Payment describes the instruction or process by which value is directed from one party to another.
Settlement occurs when the relevant obligation is discharged according to the rules of the system and the resulting position becomes authoritative and final.
The distinction sounds technical.
It is not.
It determines what the parties ultimately hold, which institutions remain between them, where exposure continues to exist, and what still has to happen after the interface says:
Paid.
The interface can finish before settlement does
A card transaction makes the distinction unusually easy to see.
The merchant receives approval within seconds. The customer sees the transaction. The purchase proceeds.
From the user’s perspective, the event is over.
Behind that experience, obligations between issuers, acquirers, networks and other participants may still have to be cleared and settled.
The interface says:
Paid.
The infrastructure may still be saying:
Obligations recorded. Settlement pending.
There is nothing defective about this arrangement. It is simply how many payment architectures work.
The error begins when the visible payment event and the underlying settlement event are treated as the same thing.
They are not.
Speed is not finality
Digital finance has made payment remarkably fast.
That matters.
But speed measures how quickly an instruction, message or provisional state can move.
Finality answers a different question:
At what point is there nothing further that must occur for the relevant obligation or ownership change to be complete?
A transaction can be communicated in milliseconds while settlement occurs later.
A system can also provide strong finality without appearing instantaneous to the user.
This distinction matters because financial technology is frequently evaluated through the interface.
How quickly did the confirmation appear?
How few clicks were required?
How smooth was the experience?
Those are useful questions.
They do not tell us whether the settlement asset changed, whether exposure between participants remains, or whether another institution still has to perform.
A faster interface may reduce friction.
It does not necessarily reduce dependency.
The more revealing question is:
What became final when the message arrived?
The settlement asset determines what the transaction ends in
Every settlement architecture ultimately relies on something participants recognise as completing the obligation.
That is the settlement asset.
Depending on the system, settlement may ultimately occur through commercial bank money, central bank money, securities, property rights or another recognised asset.
Each structure carries different dependencies.
A commercial bank deposit is a liability of the bank.
Central bank money is a liability of the central bank.
A security depends on the legal, custody and settlement architecture through which rights to it are maintained and transferred.
A physical asset may exist independently of the institutions recording ownership, but transferring rights to it still requires rules that determine authority and finality.
These arrangements are not equivalent.
To understand a financial system, therefore, it is not enough to ask how payment is initiated.
We must follow the transaction to its endpoint and ask:
What asset actually settles the obligation?
That question reveals where finality resides and who continues to carry risk before it is reached.
Clearing tells us what is owed. Settlement ends what is owed.
Clearing and settlement are also different processes.
Clearing determines the obligations between participants.
Settlement discharges them.
A system may therefore process a very large number of payments while settling only the resulting net positions later.
That can be highly efficient.
It also creates an interval between the visible payment activity and final discharge of the underlying obligations.
During that interval, participants may still be exposed to one another or dependent on infrastructure that has not yet completed its work.
Under normal conditions, the interval can be almost invisible.
Under stress, it becomes part of the architecture.
If a participant fails after payment instructions have been accepted but before outstanding obligations have been settled, the distinction ceases to be theoretical.
Payment happened.
Settlement did not.
Funding a payment is not the same as settling with the asset
The settlement-asset distinction becomes particularly clear when one asset is used to fund a transaction that ultimately settles in another.
Consider physical gold.
An owner sells gold.
Bank money is credited.
That bank money is then used to complete a conventional payment.
Gold supplied the economic value.
But the transaction settled in bank money.
Gold funded the payment. It did not settle the transaction.
That distinction matters because funding and settlement belong to different architectural layers.
If asset A must first become asset B before an obligation can be finally discharged, asset A is not functioning as the settlement asset in that transaction.
This is where phrases such as “gold payment”, “asset-backed payment” or “gold spending” can become imprecise.
Making an asset spendable is one problem.
Making the asset itself the thing in which settlement becomes final is another.
The first concerns the interface and funding path.
The second concerns ownership and finality.
Intermediaries matter most when the architecture makes them disappear
Intermediaries are often discussed as if they were merely technical routing choices.
They are not.
They may provide authentication, compliance, liquidity, custody, clearing, reconciliation, recordkeeping and risk management.
Many of those functions are necessary.
What matters is whether the architecture makes those dependencies visible.
A system may present itself as instant, direct or even peer-to-peer while still relying on several institutions underneath the interface.
Indeed, the more seamless the user experience becomes, the easier it is to forget that these institutions exist at all.
That is the paradox.
An intermediary can become most important precisely when the interface makes it least visible.
The proper question is therefore not whether intermediaries exist.
It is:
What does each intermediary still have to do before settlement becomes final?
If nothing further is required, settlement has occurred.
If another institution must still approve, fund, clear, reconcile or release value, the transaction is not yet finished simply because the user has received confirmation.
Physical assets expose the settlement boundary
Physical assets make the payment-settlement distinction particularly clear.
Suppose two parties transact using allocated physical gold.
The metal does not need to travel from one vault to another for settlement to occur.
What matters is whether ownership changes.
A payment instruction may initiate that process.
It is not the process itself.
For settlement to occur, the architecture must determine:
who owned the metal before the transaction;
who owns it afterwards;
which record is authoritative;
whether the instruction was valid;
and at what point the ownership change becomes final.
This is why a digital interface cannot create settlement merely by changing a displayed balance.
The interface can authenticate an instruction.
Software can register a transfer.
Systems can reconcile records and provide auditability.
But the architecture must still establish the meaning of the transfer and the point at which it is final.
For a physical asset, the boundary becomes unusually clear:
Payment initiates the change. Settlement completes the change of ownership.
The asset may remain exactly where it is.
The owner does not.
The same architectural questions return
The first essay asked who owns an asset and who controls the path to its use.
The settlement question applies the same discipline to a transaction.
Not:
How quickly did the payment move?
But:
What remains to happen?
Which institution still has to perform?
What asset ultimately settles the obligation?
Which record becomes authoritative?
And when does the resulting position become final?
These are not separate curiosities.
They are different views of the same architecture.
Ownership without access can leave an asset operationally unusable.
Payment without settlement can leave an instruction operationally incomplete.
In both cases, the interface may suggest that the important event has already occurred.
The architecture tells us whether it actually has.
A more demanding test
Payment systems are commonly compared by speed, cost, convenience and reach.
Those metrics matter.
But they describe only part of the system.
A more demanding test asks:
What is the settlement asset?
What obligations remain after the user sees “payment complete”?
Which institutions must still perform?
And what exactly becomes final?
Two systems can look almost identical from the outside while having entirely different answers.
Payment is what the participant sees happening.
Settlement is what the architecture makes irreversible.
The two can occur close together.
They can occur in the same technical workflow.
They can even appear simultaneous.
But they remain conceptually distinct because they answer different questions.
Payment moves instructions.
Settlement makes the resulting obligation or change of ownership final.
Any financial architecture that fails to distinguish between the two risks mistaking movement for completion.
Petro Golovko Sc.D., Ph.D.
Invisible Architecture Press